
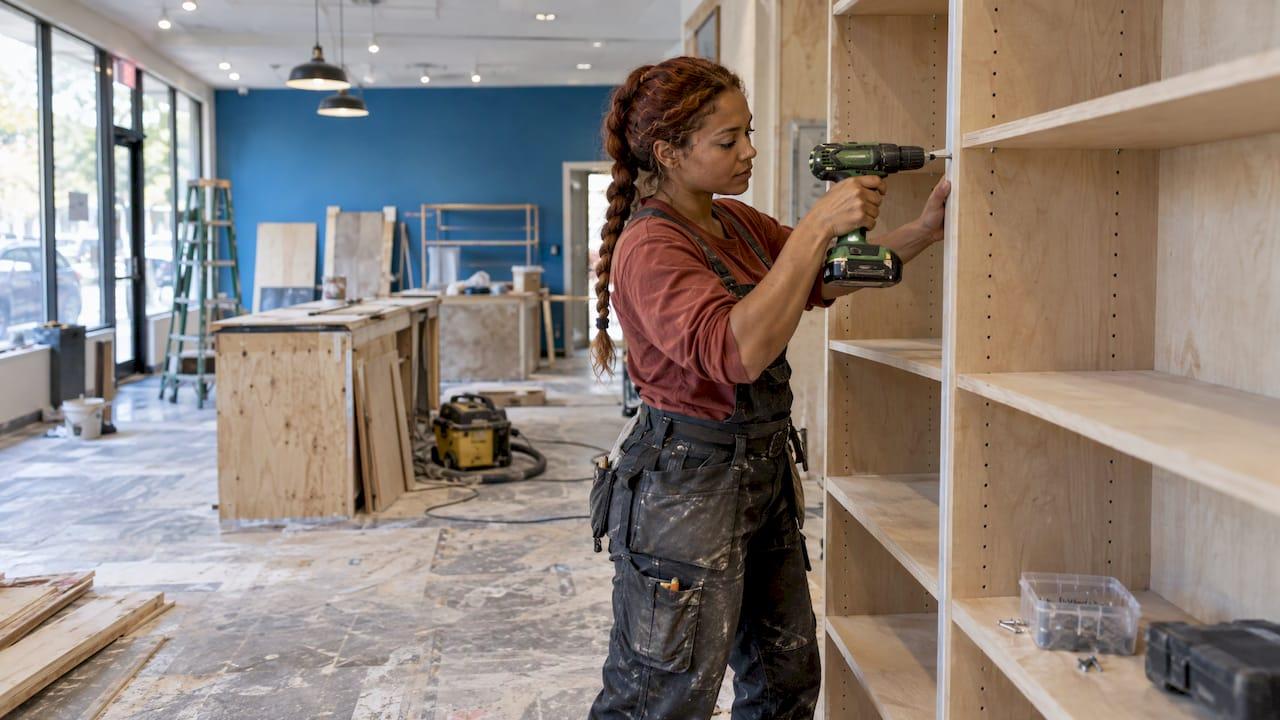
The best way to finance a retail renovation is to match each part of the project to the product built for it: equipment financing for fixtures and machinery, a business line of credit for phased work and surprises, and a term loan or SBA loan for the larger build-out. We work with retailers on exactly this kind of split, and our funding solutions cover each piece, with funding as soon as 24 hours on products where speed matters. The sections below show what each option pays for, what lenders look at, and how to prepare a leased space before you borrow.
- ✓Equipment financing
- ✓Working capital
- ✓Business line of credit
- ✓Small business loans
TL;DR
- Break the renovation into three buckets (build-out, equipment and fixtures, working capital) and finance each with the product that fits it.
- SBA 7(a) loans can fund building improvements, equipment, fixtures and working capital, up to $5 million. SBA 504 loans suit larger projects.
- If you lease your store, get the landlord's consent and lease terms in order before you apply. Lenders often need them.
- Our published starting rates: equipment financing from 0.8% per month, business line of credit from 1.2% per month, term loans from 7%, SBA loans from 6%.
Table of Contents
- What a retail renovation really costs you
- Your financing options, matched to the work
- Which option fits which renovation
- What lenders look at
- Renovating a leased space: sort out the lease first
- How to finance your renovation, step by step
- Estimating payments and comparing costs
- Retail-specific tips
- Our perspective
- Funding your store renovation with Capital for Business
- FAQ
- Sources
What a retail renovation really costs you
A remodel is never a single expense. A shop owner who prices only the contractor's quote usually runs short, because the real budget has three layers.
- The build-out. Flooring, lighting, walls, ceilings, HVAC and electrical changes, plumbing, storefront and signage. These are the improvements that stay with the building.
- Equipment and fixtures. Shelving, display cases, point-of-sale systems, refrigeration, security cameras and checkout counters. These can be moved or resold, which matters to lenders.
- Working capital. Rent and payroll while the store is partly closed, temporary inventory storage, permits, marketing for the reopening, and the cost overrun almost every project hits.
Separating the three matters because different financing products are priced and structured for each one. Using a single expensive, short-term product to cover all three is the most common way retailers overpay.
A sample budget
Here is an illustration, not a quote. Say a clothing retailer plans a $120,000 refresh:
| Budget layer | Example amount | Typical fit |
|---|---|---|
| Build-out (floors, lighting, fitting rooms) | $60,000 | Term loan or SBA loan |
| Fixtures, racks, new POS system | $45,000 | Equipment financing |
| Reopening inventory, marketing, overruns | $15,000 | Business line of credit |
The split lets each loan be sized to its purpose, and it keeps the line of credit available for the surprises that renovation brings.
Your financing options, matched to the work
Equipment financing for fixtures, displays and machinery
Equipment financing is the simplest place to start because the equipment itself usually serves as the collateral. That means the loan can be smaller in risk terms and easier to approve than a loan secured by nothing specific. It fits shelving systems, coolers, POS hardware, kitchen equipment for a cafe corner inside a store, and similar purchases.
Our equipment financing is offered up to $250,000, and the starting rate we publish is 0.8% per month. If you are weighing a purchase against a lease for fixtures, our guide on equipment leasing versus equipment financing walks through the difference, and 6 examples of equipment financing options shows how other small businesses have structured it.
A business line of credit for phased work and overruns
Renovations rarely go on a perfect schedule. A line of credit lets you draw only when a contractor invoice arrives, so you pay interest on what you have used rather than on a lump sum sitting in your account. It also absorbs the change orders, permit delays and extra materials that no quote includes.
Our business line of credit is available up to $250,000, with rates starting at 1.2% per month. For retailers whose renovation spans several months or happens in stages, this is often the most flexible piece of the stack. The Ins and Outs of Business Lines of Credit explains how draws and repayment work.
Term loans for the build-out
A business term loan gives you a lump sum with a fixed repayment schedule, which suits a defined project with a known cost: a new floor plan, a storefront rebuild or a full interior refresh. Predictable payments make it easier to forecast against the added sales you expect from the improved store. Our business term loans start at 7%.
SBA loans for larger or longer-term projects
When the renovation is substantial, SBA-backed loans are worth a serious look because of their long repayment terms. The SBA's 7(a) program allows loans up to $5 million, and the proceeds can be used to improve real estate and buildings, buy equipment and fixtures, and fund working capital. According to the SBA's lender resources page, eligible uses include leasehold improvements and expanding or renovating facilities. Terms are generally 10 years or less, and up to 25 years for real estate or for equipment with a useful life over 10 years. Rates are negotiated between borrower and lender, within SBA maximums.
Most 7(a) term loans are repaid in monthly principal-and-interest payments from business cash flow. On a fixed-rate loan the payment stays constant, while a variable-rate loan can change when the rate changes, as the SBA explains.
The SBA 504 program is built for fixed assets. It can fund the purchase, construction or renovation of existing buildings or land, and long-term machinery and equipment with at least 10 years of remaining useful life. Repayment terms of 10, 20 and 25 years are available. A retailer who owns the building and is planning a major renovation is the typical fit. For a side-by-side look, read SBA 504 vs 7(a): which loan fits your business.

Both programs are public-private partnerships. According to the SBA's 2025 Annual Report, about 5,000 private lenders originate and service the loans, while the SBA provides a government guarantee that reduces lending risk. That guarantee is why SBA terms can be longer than conventional ones. Our SBA loans start at 6%.
Smaller projects: SBA microloans
For a modest refresh, the SBA Microloan program provides loans up to $50,000 through nonprofit intermediary lenders. Per the SBA lender resources page, proceeds can cover working capital, inventory, supplies, furniture, fixtures, machinery and equipment. Each microloan must be repaid within six years, and no borrower may owe an intermediary more than $50,000 at one time.
Working capital loans and revenue-based financing
If you need money quickly and the project is partly about keeping the doors open during construction, working capital funding covers payroll, rent and inventory. Our working capital loans start at 1.5% per month, and our revenue-based financing starts at 1.8% per month, with repayment tied to your sales. Both are described on our funding solutions page. For a store with steady card sales, they can bridge the weeks when renovation cuts into revenue.
Which option fits which renovation
| Situation | Best-fit product | Why |
|---|---|---|
| New shelving, displays and POS | Equipment financing | The equipment secures the loan |
| Cosmetic refresh done in stages | Business line of credit | Draw as invoices arrive |
| Defined build-out with a fixed quote | Term loan | Predictable payments |
| Major renovation, long payback | SBA 7(a) or 504 | Long terms, up to 25 years for real estate |
| Store open during work, sales dip | Working capital loan | Covers rent and payroll gaps |
| Owner with past credit problems | Bad credit business loan | Broader credit profiles considered |
For owners whose credit profile has stopped them at the bank, we offer bad credit business loans starting at 2.5% per month.
What lenders look at
Whatever product you choose, lenders are answering one question: can this business repay? You can shorten the process by preparing the following before you apply.
- Business financials. Recent bank statements, a profit and loss statement, and tax returns. Lenders compare your cash flow to the new payment.
- A project scope and budget. A contractor's written quote, a list of equipment with prices, and a timeline. This also shows the lender which loan product matches which cost.
- Time in business and revenue. Lenders generally want to see an operating history that supports the loan size.
- Collateral and guarantees. Equipment can secure an equipment loan. For larger loans, expect a lien on business assets.
SBA loans have written eligibility rules. The SBA says a 7(a) borrower must be an operating, for-profit business in the U.S., small under SBA size requirements, not an ineligible business type, unable to obtain the credit on reasonable terms from non-government sources, and creditworthy with a reasonable ability to repay.
On collateral, an overview of the 7(a) program from the Minority Business Banking Association (April 2026) states that SBA requires lenders to take a first lien on business assets, specific liens on collateral valued over $5,000, a first-lien mortgage on financed commercial property, and personal guarantees from all owners of 20% or more. It also notes that lack of collateral does not automatically end a deal, though borrowers must pledge all available collateral. Our guides on SBA loan collateral and SBA 7(a) requirements go through this in more detail, and collateral explained covers it for other products.
Renovating a leased space: sort out the lease first
Many retailers rent. Financing improvements to a space you do not own is possible, but the lease becomes part of the loan file. Check these points before you borrow.
- Landlord consent. When an SBA loan finances improvements on leased property, the lender may take a lien on your leasehold interest. According to Starfield & Smith, a law firm that writes on SBA lending, SBA rules require the landlord's written consent to the leasehold mortgage and collateral assignment.
- The right to pledge the lease. The same source notes the lease needs provisions allowing the tenant to encumber the leasehold, and barring changes or cancellation without lender approval.
- Lease term. A loan should not outlast your right to occupy the space. If you have three years left on the lease and a ten-year loan, negotiate an extension first.
- Tenant-improvement allowances. If your landlord reimburses part of your build-out after completion, tell the lender. Starfield & Smith explain that SBA rules restrict using loan proceeds for payments to an associate of the applicant, so lenders commonly require the reimbursement to pay down the loan principal and may take an assignment of the allowance.
- Who owns the improvements. Many leases say fixtures attached to the building belong to the landlord at lease end. That affects what you can use as collateral and how you value the project.
Lease terms differ by state, and a commercial lease is a legal contract, so have a real estate attorney review yours before you sign an extension or a consent form. For a sense of the clauses that matter to small tenants, this overview of commercial lease clauses to negotiate is written around Florida law, but the clause checklist is a useful starting point for any tenant.
How to finance your renovation, step by step
1. Set the scope and get written quotes
Get at least two contractor quotes and an itemized equipment list. Add a contingency. A reserve for overruns is a working capital need, and it is easier to finance up front than to scramble for during the project.
2. Sort costs into the three buckets
Use the build-out, equipment and working capital split from the sample budget above. This tells you how much of the total belongs on each product.
3. Check the lease or the deed
If you rent, collect the lease, the landlord's contact and any improvement allowance details. If you own, have the property documents ready, since real estate loans and SBA 504 financing rely on them.
4. Gather your documents
Bank statements, tax returns, a profit and loss statement, your business registration and an ID. Having these ready is what keeps a request moving.
5. Apply for the product that matches the time frame
If you must start in weeks, equipment financing, a line of credit or working capital can move quickly. We state that funding can arrive as soon as 24 hours on our products. A large SBA loan typically involves more documentation and a longer process because a lender underwrites the full financial picture, so start earlier.
6. Plan how contractors are paid
With a lump-sum loan, schedule payments to the contractor against milestones. With a line of credit, draw per invoice. With SBA 504, the project funding is split among the SBA-backed portion, a third-party lender and your own contribution. The SBA's Form 1244 shows that the borrower contribution must be cash or project property, cannot come from an SBA loan program, and that no more than 50% of eligible project costs may come from federal sources.
7. Set up repayment
Loan servicing for an active 504 loan runs through a Central Servicing Agent, usually by monthly ACH draws, as the SBA's 504 page states. Build the payment into your monthly budget before the renovation completes, so the added debt does not arrive as a surprise.
Estimating payments and comparing costs
The quoted rate is only part of the picture. Compare offers on these points:
- Rate type and basis. Some products quote a monthly rate and others an annual one. A 1.2% monthly rate is not comparable to a 7% annual rate until you put both on the same basis.
- Term. A longer term lowers the payment but increases total interest.
- Fees. Ask for origination or closing fees in writing.
- Prepayment. Find out whether paying early saves interest or triggers a fee.
- Fixed or variable. Fixed payments are easier to plan around. As the SBA notes, variable-rate payments can change when the rate changes.
To estimate whether the renovation pays for itself, compare the monthly payment with the extra gross profit you expect from higher sales, more foot traffic or a larger floor display area. If the loan payment is covered by conservative sales estimates, the project is on safer ground. A rough check: take the payment, divide by your gross margin, and see what additional monthly sales it requires.
Our published starting rates are on our funding solutions page, and the final rate depends on your application.
Retail-specific tips
Time the work around your season. A holiday-driven store should finish before fall inventory arrives, which means financing needs to be in place months earlier. Funding speed helps if a deadline moves.
Keep inventory separate from build-out. Do not drain the cash you need for stock to pay a contractor. A line of credit covers the gap between paying suppliers and selling goods.
Protect your sales during construction. Phase the work if you can, keep part of the store open and put a reopening campaign in the budget.
Look at card-sales-based funding when sales are strong. Retailers with consistent card volume can use products tied to sales. Our merchant cash advance page explains how that works.
Our perspective
We have worked with business owners in hundreds of different industries since 2009, and renovations are one of the places where the right financing structure makes the biggest difference. Retailers tend to approach a remodel as one number. We encourage them to see three: the build-out, the equipment and the working capital that keeps the store running.
That is why we offer a range of products rather than one. Equipment financing from 0.8% per month fits fixtures. A business line of credit from 1.2% per month handles invoices and overruns. Term loans from 7% and SBA loans from 6% suit the larger build-out. When a bank or credit union turns an application down, we are designed to offer another route, including for a range of credit profiles.
Speed matters in retail because a delayed reopening costs sales. Our aim is funding as soon as 24 hours where the product allows, so a remodel stays on its schedule. We work with owners nationwide and in Canada, and we would rather match you with the right combination than push a single product.
Capital
Funding your store renovation with Capital for Business
We offer equipment financing, business lines of credit, working capital loans, term loans and SBA loans, so one provider can cover every layer of your remodel. Our retail business loans provide funding up to $500,000, and you can compare every product on our funding solutions page.
If you have your quote and equipment list ready, you can start an application from our home page. For background on how the $10M SBA change affects retailers, see our post on retail business financing options.
FAQ
Can I get a loan to renovate a store I rent?
Yes. Both SBA 7(a) proceeds and other business financing can fund improvements to leased premises. Lenders will want to see your lease, and for SBA loans the landlord's written consent to a leasehold lien is typically required. Review the lease with a real estate attorney first.
What is the monthly payment on a $50,000 business loan?
It depends on the rate, term and fees. As an illustration, the same $50,000 costs less per month over a longer term but more in total interest. Most 7(a) term loans are repaid in monthly principal-and-interest payments, and a fixed rate keeps that payment constant. Ask for the full repayment schedule before you accept an offer.
Can I finance new fixtures and equipment separately from the build-out?
Yes, and it is often the better choice. Equipment financing is built around the equipment you are buying, which usually serves as the collateral. Our equipment financing goes up to $250,000 and starts at 0.8% per month, leaving your other credit available for the construction work.
Can I qualify with bad credit?
Possibly. We offer bad credit business loans starting at 2.5% per month for owners who were declined elsewhere. Strong recent revenue helps, and a smaller, equipment-secured request can improve the odds.
Which is better for a renovation, SBA 7(a) or SBA 504?
SBA 504 is designed for fixed assets such as buildings, land and long-life equipment, with terms of 10, 20 and 25 years. SBA 7(a) is more flexible, covering real estate improvements, equipment, fixtures and working capital. A retailer who wants one loan to cover build-out and reopening costs often leans toward 7(a), while an owner renovating a building they own may fit 504.
Sources
- 7(a) loans, U.S. Small Business Administration
- SBA lender resources: partnering with SBA loan programs
- 504 loans, U.S. Small Business Administration
- SBA 2025 Annual Report
- SBA 7(a) Financing: An Overview for Business Brokers, MBBA, April 2026
- Best Practices: Considerations for SBA Loans Financing Improvements on Leased Land, Starfield & Smith
- Best Practices: Leasehold Improvements with Tenant Improvement Allowance, Starfield & Smith
- SBA Form 1244, Application for Section 504 Loan
- Commercial lease clauses to negotiate