
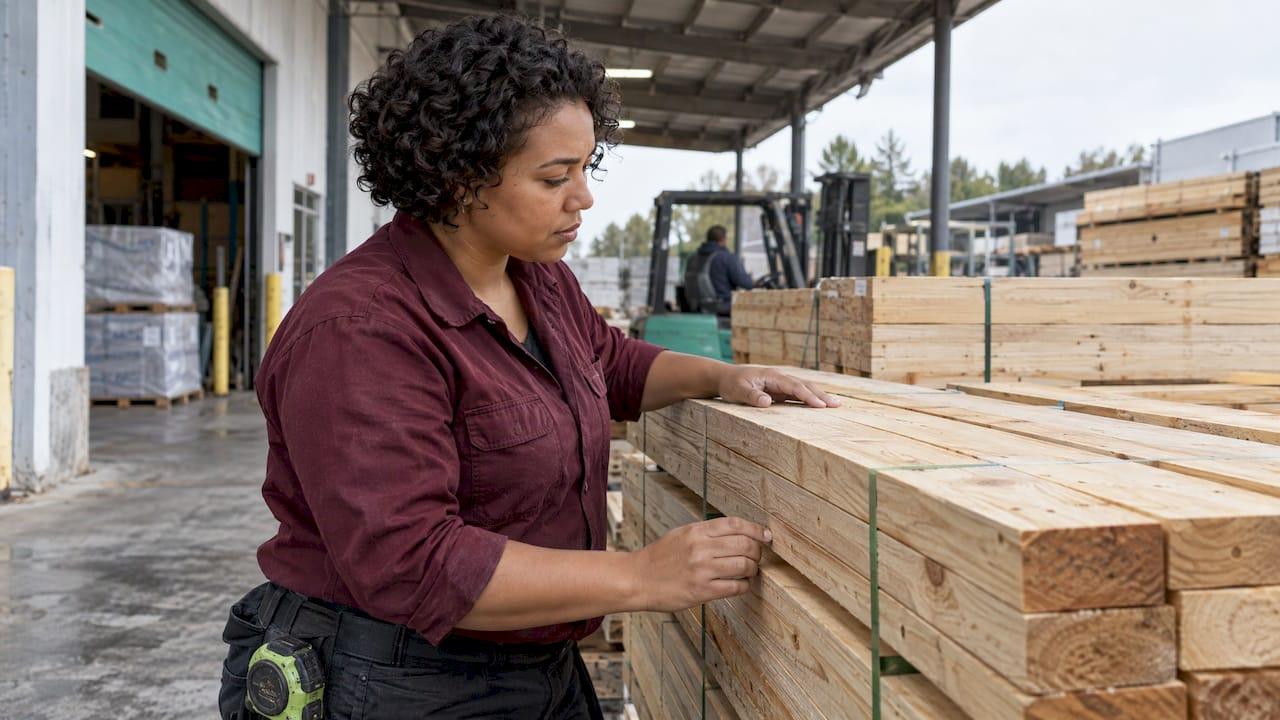
A business line of credit works best for short-term, variable costs: covering payroll while a customer's payment is late, buying inventory ahead of a busy season, paying for materials before a job is billed, or handling a repair you did not plan for. You draw only what you need, repay it, and borrow again up to your limit. It is a poor fit for one large, one-time purchase, where a term loan or equipment financing usually suits better.
This guide walks through the most common uses, how a line of credit behaves in each situation, what to check before you draw, and the uses to avoid. It pays particular attention to contractors, inventory-heavy businesses and payroll, because those are the situations owners ask about most.
TL;DR
- A line of credit fits costs that rise and fall: seasonal cash flow, late-paying invoices, inventory, short-term payroll gaps and unexpected repairs.
- Interest is charged on the amount you draw, not on the whole limit, and repaid funds become available again, subject to your agreement's terms.
- Contractors use lines of credit to buy materials and pay crews between progress billings.
- For a large, planned purchase such as a major piece of equipment, compare a term loan or equipment financing first.
- Avoid using a line to cover a permanent shortfall. If you draw every month just to break even, fix the underlying cause first.
Table of Contents
- How a business line of credit works, in short
- The best uses of a business line of credit
- Line of credit for contractors
- When to use a line of credit, and when to choose something else
- How draws, interest and fees work
- Uses to avoid
- A step-by-step way to decide whether to draw
- Our perspective
- Apply for a line of credit
- FAQ
- Sources
How a business line of credit works, in short
A line of credit is a revolving credit facility. A lender approves a credit limit, and you draw from it as needs arise. Each repayment restores part of your available balance, so you do not reapply every time you need cash.
Three features shape every use case below:
- Draws: You request funds when you need them, in amounts of your choosing up to your available limit.
- Interest: You pay interest on the outstanding balance. Unused credit generally does not accrue interest, though your agreement may include other fees.
- Repayment: Repaying the balance frees up credit for the next need. Repayment schedules differ by lender and product, so read the terms before you sign.
Our own business line of credit is published at rates starting from 1.2% per month, and our lines of credit page describes limits up to $250,000. Your actual limit and rate depend on your application, your revenue and your credit profile.
If you want a fuller walkthrough of the mechanics first, our guide to what a business line of credit is covers the basics in more depth.
The best uses of a business line of credit
Accounting software provider Xero describes a line of credit as suited to short-term, variable funding needs rather than large one-time purchases, and lists seasonal cash flow, invoice gaps, inventory opportunities, equipment repairs and short-term marketing among the common uses. The sections below take each in turn and add what it looks like in practice.
1. Smoothing out seasonal cash flow
Many businesses earn most of their revenue in a few months, yet pay rent, utilities, insurance and staff all year. A landscaper in winter, a flower shop after Mother's Day, a retailer in January and a roofer in a rainy month all face the same pattern: expenses arrive on schedule, and sales do not.
A line of credit lets you draw during the slow stretch and repay during the busy one. Because you pay interest only while the balance is outstanding, a well-timed draw costs far less than keeping a large balance all year.
A practical way to plan this:
- Look at your last 12 months of deposits and expenses and mark the months where cash dips below your fixed costs.
- Add up the shortfall in each of those months.
- Compare the total to your credit limit. If the peak shortfall fits comfortably, the line is a good match.
- Set a repayment target tied to your next strong sales period.
For more on this pattern, see our article on seasonal business funding for small businesses.
2. Bridging gaps while invoices go unpaid
If you sell on terms of 30, 45 or 60 days, you do the work now and get paid later. Meanwhile payroll, suppliers and taxes do not wait. A line of credit can cover the gap: draw when the bill is due, repay when the customer's payment lands.
This is one of the cleanest uses because the repayment source is already known. The invoice is the plan. If the customer is reliable, the draw is short and cheap.
If a large share of your revenue is tied up in unpaid invoices for long stretches, it may be worth comparing a line against invoice factoring, which advances cash against the invoices themselves. Our published factoring pricing runs 0.69% to 4.9% per invoice.
3. Buying inventory
Inventory is where a revolving line shines for retailers, distributors and restaurants. Suppliers often offer better pricing for larger orders or early buys, and a line lets you take advantage without draining your operating cash.
How the cycle works:
- You draw the amount needed for a purchase order.
- The goods arrive and sell.
- Sales revenue repays the draw, and the credit is available again.
The key is turnover. If you can expect the stock to sell within weeks or a few months, the draw is repaid quickly and the interest is a modest cost against the margin you earn. Slow-moving stock is a different story: if goods sit for a year, the interest keeps running while the cash is locked up. Match the size of the draw to how fast you realistically sell.
Typical inventory uses include:
- Stocking up before a holiday or peak season
- Taking a supplier's volume discount
- Restocking quickly after an unexpectedly strong sales week
- Replacing items that are hard to get on short notice
4. Covering payroll during a temporary gap
Can a line of credit pay your employees? Yes, a draw is cash, and most business lines of credit are not restricted to particular expenses. Payroll is one of the most common reasons owners reach for one, usually because a customer paid late or a seasonal slowdown arrived before the busy period.
There are a few things to think through before you draw for payroll:
- Is the gap temporary? A draw works when you know where the repayment will come from, such as an invoice due next week or a seasonal rebound.
- How long will the balance stay open? Payroll is a recurring cost. If you borrow for it every cycle, the balance grows instead of shrinking.
- Do you have enough room? Make sure your available limit covers the payroll run plus your other draws.
- What are the payroll taxes? Payroll taxes are due on their own schedule. Talk to your accountant about the timing so a draw covers them in time.
Used as a bridge, a line keeps your team paid on time without scrambling. Used as a standing substitute for profit, it becomes a warning sign (more on that below).
5. Handling equipment repairs and replacements
A compressor fails, a delivery van needs a transmission, a commercial oven goes down on a Friday. These costs are unplanned, urgent and often too small to justify a separate loan application. A line of credit gives you cash within your agreement's terms, so the business keeps running.

For larger purchases, the picture changes. A big, planned piece of machinery is usually better matched with equipment financing, which spreads the cost over a fixed term. Our equipment financing is published from 0.8% per month. If you are weighing the options, our guide on choosing between a small business loan or equipment leasing lays out the tradeoffs.
6. Short-term marketing and sales pushes
A promotion, a trade show booth or a seasonal ad campaign costs money before it brings in revenue. If you have a clear sense of the return, such as a past campaign that produced predictable sales, a draw can fund the spend and be repaid from the resulting sales.
Keep this use to campaigns you can measure. Open-ended brand spending with no clear payback window is better funded from profit.
7. Taking advantage of discounts and opportunities
Sometimes a supplier offers a bulk price for a limited time, or a competitor liquidates stock, or a client asks for a rush order that needs materials fast. Having a line available means you can say yes quickly. An opportunity that needs cash in days does not leave time for a new loan application.
This is a quiet benefit of a line: it is most valuable when you have it before you need it. Many owners open one while the business is performing well, so it is there in a slower month.
Line of credit for contractors
Contractors have a cash flow pattern few other industries share. You pay for labor and materials up front, then bill the client in stages, often with retainage held until completion. A project can be profitable on paper and still leave you short of cash for weeks.
A line of credit is a natural tool here. Common contractor uses include:
- Materials before billing: Buy lumber, wire, pipe, ductwork or fixtures for a job and repay when the progress payment comes in.
- Crew payroll between draws: Keep subcontractors and employees paid on schedule while a payment is pending.
- Mobilization costs: Cover permits, deposits, rentals and the first stretch of work on a new job.
- Bridging retainage: Cover the gap while a portion of your payment is held until the job closes out.
- Bidding on more than one job: Take on a second project without waiting for the first to pay.
Here is a simple worked example. Suppose an HVAC contractor wins a job with a $40,000 contract. Materials and labor for the first phase cost $14,000, and the first progress payment is due in 30 days. Drawing $14,000 lets the crew start immediately. When the progress payment arrives, the contractor repays the draw, and the credit is available for the next phase or the next job. The interest cost is the rate applied to the balance for the time it was outstanding.
You can read more on this in our article on why contractors need business loans to manage cash flow.
A few cautions specific to contractors: price your bids to include financing costs, keep a draw tied to a specific job when you can, and track repayment against each project's payment schedule. That way you always know which job is paying back which draw.
When to use a line of credit, and when to choose something else
The simplest rule is to match the type of funding to the type of need. Xero recommends a line of credit for cash flow management, unpredictable needs and short-term expenses, and notes that a term loan may suit large purchases and predictable costs better.
| Situation | Usually a good fit | Why |
|---|---|---|
| Payroll gap while an invoice is pending | Line of credit | Short, known repayment source |
| Seasonal inventory build | Line of credit | Stock sells, balance repays |
| Unplanned repair | Line of credit | Fast access, no new application |
| Large, one-time equipment purchase | Equipment financing or term loan | Fixed term matches the asset's life |
| Expansion, build-out or acquisition | Term loan or SBA loan | Larger amount, longer repayment |
| Invoices consistently slow to pay | Line of credit or invoice factoring | Depends on volume and customer terms |
| Ongoing revenue-linked funding needs | Revenue-based financing | Repayment follows sales |
For the bigger-ticket cases, take a look at our business term loans, published from 7%, and our SBA loans, published from 6%. If you are undecided, our article on whether a loan or a line of credit is right for a small business walks through four key questions.
If you are comparing a line against a credit card for everyday spending, see our comparison of a business line of credit vs. a credit card.
How draws, interest and fees work
Before you use a line for any of the purposes above, understand the moving parts.
Drawing funds
You request a draw up to your available limit. Some lenders deposit the funds into your business bank account, and the process is usually quicker than a new loan application. Ask how quickly a draw reaches your account, and whether there is any minimum or maximum draw size.
Interest
Interest accrues on the amount you have drawn. For a simple illustration with round numbers, say you have a $50,000 limit and draw $10,000. Interest applies to the $10,000, not the $50,000. If your rate is 1.2% per month, which is the starting rate we publish, a $10,000 balance held for a month would accrue about $120 in interest at that rate, and your actual rate may differ. Pay the balance down sooner and the cost falls.

Because rates on lines are often quoted monthly, convert them to an annual figure when you compare against a term loan quoted as an annual rate. Multiplying a monthly rate by 12 gives a rough annual equivalent, and your lender can give you the precise figure.
Fees
Depending on the product, a line of credit can come with origination, maintenance, draw or renewal fees. Read the full fee schedule and add it to the rate when you estimate your real cost. This is a normal part of comparing any financing, and a clear schedule makes planning easier.
Repayment
Repayment terms vary: some lines ask for regular payments on the balance, others set a schedule for each draw. Know which one applies to you and set reminders so you never miss a payment. On-time repayment also helps keep your line available for the next need.
Uses to avoid
A line of credit is flexible, which also means it can be misused. These are the situations to steer clear of.
- Funding a permanent loss. If you draw every month to cover expenses that revenue does not meet, the balance only rises. Fix pricing, costs or sales first.
- Long-term assets on short-term credit. Using a revolving line to buy something that will take years to pay for itself creates a mismatch. Choose a term product instead.
- Paying off one revolving balance with another without a plan. Moving debt around does not reduce it. Have a repayment plan before you draw.
- Speculative spending. Draws are best tied to a known return or repayment source.
- Maxing the line. Keep room in reserve so you can handle a surprise.
A useful self-check: before any draw, write down where the repayment will come from and when. If you cannot answer, pause.
If you find yourself using a line mainly for daily card-style spending, it is worth reviewing how you manage business expenses overall. This business credit card and spend management comparison can help you think about how to separate routine spending from borrowing.
A step-by-step way to decide whether to draw
- Name the need. Payroll, inventory, materials, repair or opportunity.
- Name the repayment source. An invoice, a season's sales, a project payment.
- Set the timeline. How many days or weeks until the balance is repaid?
- Check the cost. Rate, fees and the interest for the expected period.
- Check the cushion. Will you still have available credit after the draw?
- Draw only what you need. The point of a line is that you do not borrow the full limit.
Our perspective
We have worked with small business owners since 2009, across hundreds of industries, and the same pattern shows up again and again: the businesses that handle growth well are rarely the ones with the most cash. They are the ones that know when cash will arrive and have a way to cover the gap until it does.
That is what we believe a line of credit is for. It is a tool for timing. A contractor waiting on a progress payment, a retailer building stock for the holidays and a restaurant owner covering a slow month all need money for a short period, then need it back in reserve for the next time. A revolving line is designed for that rhythm.
We also know that banks and credit unions do not say yes to every good business. Our approach is designed to work with a broad range of credit profiles, and we aim to fund as soon as 24 hours after approval, because a gap in cash flow rarely waits for a slow process. Our line of credit, published from 1.2% per month, is built so you can draw what you need and keep the rest available.
Our advice is simple. Match the funding to the need, keep a repayment plan for every draw, and open a line before you are in a tight spot. Owners who have one ready tend to make calmer decisions.
Capital
Apply for a line of credit
If the uses above sound like your business, we can help you set up a revolving line sized to your cash flow. Our business line of credit is designed for payroll gaps, inventory, project costs and unplanned expenses, with limits described up to $250,000 and rates from 1.2% per month. If a different product suits your plans better, you can compare everything we offer on our funding solutions page.
Applying takes a short application, and you can start from our homepage. Approval and terms depend on your business profile.
FAQ
What is a line of credit most commonly used for?
Most owners use one for working capital: covering payroll and supplier bills while waiting for customer payments, buying inventory ahead of busy periods, and paying for unexpected repairs. These are short-term, variable costs where you borrow, repay and borrow again.
Can I use a line of credit for payroll?
Yes, funds you draw can generally be used for payroll. It works best as a bridge when you know the repayment source, such as an invoice due soon or a seasonal rebound. Ask your accountant how a draw fits with your payroll tax deadlines.
Is a line of credit good for contractors?
It often is. Contractors pay for materials and labor before they bill, and progress payments and retainage can arrive weeks later. A draw covers costs on a job and is repaid when the client pays. Tie each draw to a specific project so you can track repayment.
Can I use a line of credit to buy inventory?
Yes. It suits stock that sells within weeks or a few months, because sales repay the draw and restore your available credit. For slow-moving inventory, size the draw carefully, since interest continues while goods sit on the shelf.
When should I choose a loan instead?
Choose a term loan or equipment financing when you are making a large, one-time purchase with predictable costs and a long useful life. A line of credit is a better match for costs that vary in size and timing.